Business Funding Services in Mysore: How to Get the Right Loan for Your Business
Business Funding Services in Mysore
Business funding services in Mysore help business owners identify the right type of finance, prepare lender-ready documents, and get their loan sanctioned at the best possible terms. A funding consultant works across banks and NBFCs instead of one lender, so you compare real offers rather than accepting the first one that comes along.
This matters in Mysore specifically. The city runs on small manufacturers around Hebbal and Hootagalli, silk and handloom traders, tourism and hospitality businesses near the Palace, clinics and diagnostic centres, and a fast-growing IT services base. Each of these needs a different funding structure — and most get turned down not because the business is weak, but because the file was presented badly.
What Business Funding Services Actually Cover
Funding is not just “getting a loan.” A proper consultant handles the full chain:
Requirement assessment — how much you actually need, and for what. Over-borrowing hurts your ratios; under-borrowing means you are back at the bank in six months.
Structuring — term loan, overdraft, cash credit, or a mix.
Documentation — financials, GST returns, bank statements, ITRs, projections, and a project report the credit team can approve.
Lender matching — sending your profile to lenders whose policy actually fits your case.
Negotiation and follow-up — rate, tenure, processing fee, and pushing the file through sanction and disbursement.
Secured vs Unsecured: Which Business Funding Option Fits You
This is the first real decision, and it drives everything else.
Secured Business Funding
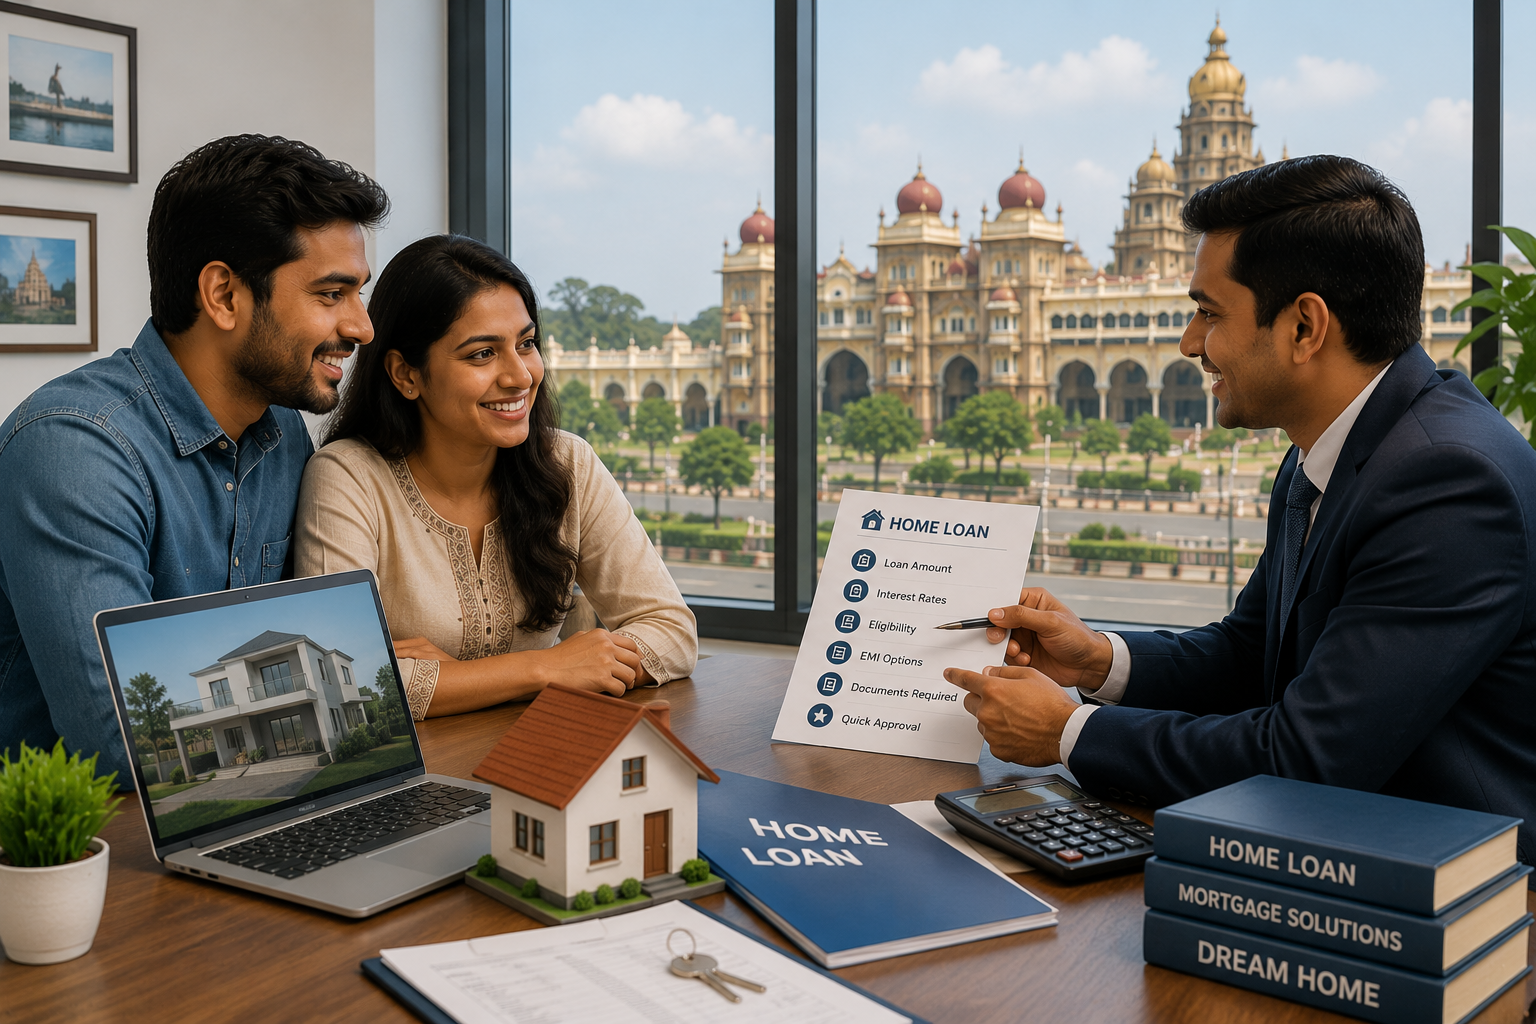
You pledge an asset — usually property, sometimes machinery or receivables. In return you get larger ticket sizes, lower interest rates, and longer tenures. A/mortgage-loan-services-in-mysore/ “mortgage loan against property”is the most common route for Mysore business owners funding expansion, a new unit, or a large equipment purchase.
Best for: established businesses, capital expenditure, amounts above ₹50 lakh, long repayment horizons.
Trade-off: slower processing, legal and valuation costs, and your asset is at risk.
Unsecured Business Funding
No collateral. Approval depends on cash flow, credit score, GST turnover, and banking history rather than what you own. Government-backed frameworks make this viable for small enterprises — MUDRA covers micro-enterprise loans up to ₹10 lakh, and CGTMSE provides guarantee cover to lenders so they can extend credit to Micro and Small Enterprises without demanding security. Coverage limits under CGTMSE were raised significantly in recent years [Insert Current CGTMSE Guarantee Ceiling 2026].
Best for: working capital gaps, inventory build-up before a season, short-term opportunities, and businesses without property to pledge.
Most Mysore businesses end up using both — a secured facility for the long-term asset and an unsecured line for month-to-month working capital. The mistake is funding a five-year asset with a two-year unsecured loan and then choking on the EMI.
Why Business Loan Applications Get Rejected in Mysore
From what lenders consistently flag, rejections cluster around a handful of fixable issues:
GST returns and ITR do not match. Credit teams cross-check turnover across both. Any gap is treated as a red flag.
Cash-heavy banking. If your declared turnover never touches your current account, the lender cannot verify it.
Weak or missing bookkeeping. No clean P&L and balance sheet means no assessment. Ordered [INTERNAL LINK: /accounting-services-in-mysore/ “accounting and bookkeeping support”] usually fixes this within a quarter.
Unregistered business structure. Proprietorships with no Udyam registration or formal entity struggle at every bank.
Too many recent enquiries. Applying to eight lenders at once drops your score and signals desperation.
No clarity on end-use. “For business growth” is not an answer a credit officer can approve.
How PM Associates Approaches Business Funding in Mysore
PM Associates operates from Chamundipuram, Mysore as a multidisciplinary firm covering accounting, taxation, audit, and finance. That combination matters for funding, because the things that get a loan approved — clean books, filed returns, correct entity structure — are the same things a CA firm handles anyway.
The approach is straightforward:
Fix the file before it goes out. Compliance gaps get closed first. That means current “GST filing and compliance“] and up-to-date “income tax returns”]—the two documents every lender pulls.
Structure the entity correctly. If you are still operating informally, “company registration” often unlocks better terms than any negotiation would.
Match, then apply. Profiles go to lenders whose policy fits, rather than shotgunning applications.
Handle the full loan arrangement. From assessment through sanction and disbursement, including “business loan services in Mysore“] across banks and NBFCs.
Because the same team files your returns and prepares your loan file, there is no gap between what you declare and what you present to a lender.
Questions to Ask Before Hiring a Business Finance Consultant in Mysore
How many lenders do you actually work with, and are they banks, NBFCs, or both?
What is your fee, when is it charged, and is it contingent on disbursement?
Will you review my GST and ITR position before applying, or just forward my documents?
Can you show me comparable cases in my sector and ticket size?
How will you protect my credit score from multiple hard enquiries?
Who handles the follow-up with the bank after submission — you or me?
A consultant who cannot answer the first and last question clearly is a lead broker, not an advisor.
FAQs:
1. What are business funding services in Mysore?
They are advisory and arrangement services that help a business identify the right finance option, prepare lender-ready documentation, and secure a sanction. The core value is lender matching and file preparation, not just form filling.
2. Can I get a business loan in Mysore without collateral?
Yes. Collateral-free business funding is available to eligible Micro and Small Enterprises through CGTMSE-backed lending and MUDRA, as well as unsecured NBFC products. Approval depends on Udyam registration, credit score, GST turnover and banking history rather than property.
3. What documents are needed for a business loan in Mysore?
Typically KYC of promoters, business registration proof, the last 12 months of bank statements, GST returns, the last 2–3 years of ITRs and financial statements, and details of existing loans. Secured loans additionally require property title documents and a valuation report.
4. How long does business loan approval take?
Unsecured loans can be sanctioned in roughly 3–10 working days if documents are clean. Secured loans against property usually take 3–6 weeks because of legal verification and valuation. Incomplete paperwork is the single biggest cause of delay.
5.Does a low CIBIL score block business funding completely?
Not always. Lenders weigh business cash flow and GST turnover alongside the promoter score, and a secured facility can still go through where an unsecured one would not. A score below the mid-600s usually means higher pricing or a collateral requirement.
Get Expert GST Registration Help in Mysore
P M Associates provides loan arrangement along with accounting, GST, income tax, audit, and other financial services.
If you want to compare the business loan interest rate and find a financing option suitable for your business, contact P M Associates in Mysore.
P M Associates provides loan arrangement along with accounting, GST, income tax, audit, and other financial services. you can find our website on google too .